how-to · 13 November 2026 · 11 min read
7 Mortgage Insurance Requirements in Nigeria to Know
By Editorial Team
Last Updated: November 12, 2026
Quick Summary
Mortgage insurance requirements in Nigeria combine legal duties on the property with lender conditions before funds are released. The building must be insured against fire and special perils, and most lenders also require mortgage protection assurance (life cover) on the borrower. Missing either can stall your loan at the final stage.
- Mortgage protection assurance pays off your outstanding mortgage balance if you die before the loan is repaid.
- Fire and special perils cover is usually required before disbursement, with the lender named as loss payee.
- Cover is based on rebuild cost, not market price; underinsuring triggers a reduced claim settlement.
- Prepare documents like six months of bank statements, a loan offer letter and a completed proposal form.
- Request written quotes from two or three NAICOM-licensed insurers and compare exclusions, not just premiums.
Table of Contents
- What Mortgage Insurance Requirements in Nigeria Actually Involve
- Mortgage Protection Assurance in Nigeria: Cover for the Borrower
- Home Insurance in Nigeria: Protecting the Property Itself
- When Insurance Is Required and Who Pays
- Mortgage Insurance Documents Required for Your Application
- Mortgage Insurance Cost in Nigeria and How Premiums Are Set
- Exclusions, Claims and Settlement: What Borrowers Should Check
- Get a Mortgage Insurance Estimate Before You Commit
- Frequently Asked Questions
What Mortgage Insurance Requirements in Nigeria Actually Involve
Mortgage insurance requirements in Nigeria are not one single rule. They are a mix of legal duties tied to your property and conditions your lender adds before it releases funds. The confusion around these requirements is real and can be costly.
Here is the short answer: the property must be insured against fire and special perils, and most lenders also require life cover on the borrower. Miss either, and your loan can stall at the final stage.
A common mistake is treating insurance as paperwork to sort out after approval. Before you commit, it helps to review the mortgage mistakes to avoid when buying a home in Lagos. In practice, the lender wants proof before disbursement.
- Property cover protects the building itself.
- Life cover protects the loan if the borrower dies.
- Lender conditions sit on top of both.
Below, we show you exactly what each requirement means, who pays, and how to prepare. And we start with the part most guides skip: the difference between what the law demands and what your bank demands.
National Insurance Commission regulatory framework
Mortgage Protection Assurance in Nigeria: Cover for the Borrower
Mortgage protection assurance in Nigeria is a life policy that pays off your outstanding mortgage balance if you die before the loan is repaid. The lender is usually the first beneficiary, and any surplus goes to your estate.
This is the cover most borrowers misunderstand. It is not savings. It is not an investment. It is a safety net for the bank.
What most guides miss is the age factor.
- Life assured: the borrower
- Beneficiary: the lender first, then your family
- Policy duration: matches your loan tenor
Watch out: some borrowers buy a policy and let it lapse after two years. A lapsed policy at the time of death leaves your family with the debt and no payout.
Home Insurance in Nigeria: Protecting the Property Itself
Home insurance in Nigeria covers the physical building against fire, flood, burglary and other named risks. It protects the asset, not the person, and the lender insists on it because the property is the loan's security.
The core policy is fire and special perils. That usually includes lightning, explosion, storm and flood damage. You can add burglary, and many owners do.
Cover is based on the rebuild cost, not the market price. Insure for too little and the insurer pays a reduced share of any claim.
- Building cover: the structure itself
- Contents cover: what you move in
- Landlord cover: for rented property
A practical point: if you buy off-plan, confirm when cover must start. Most lenders want it active from the day you take possession, not the day you sign.
When Insurance Is Required and Who Pays
The honest answer is that two different things are often conflated: what the law requires of a property owner, and what a lender requires as a condition of the loan. They overlap, but they are not the same.
What the law requires. Insurance regulation in Nigeria is overseen by the National Insurance Commission (NAICOM). Confirm the current statutory requirements and the Act governing them with NAICOM or a qualified legal adviser, as the applicable provisions should be checked against the version currently in force.
What the lender requires. On top of the legal floor, your lender will typically impose:
- Fire and special perils cover on the building, with the lender named as interested party or loss payee
- Mortgage protection assurance (credit-life) assigned to the lender, so the outstanding balance is settled on death
- Evidence that premiums are current for the life of the loan, sometimes via a standing arrangement
- A minimum sum assured tied to the loan balance or the rebuild cost, whichever the lender specifies
Who pays. Ask your lender which party is responsible for each premium and whether any premium can be added to the loan before you sign.
| Cover Type | Legal or Contractual | Who It Protects | Usually Paid By | When Required |
|---|---|---|---|---|
| Fire and special perils | Contractual (standard mortgage condition) | The property and the lender's security | Borrower | Before disbursement |
| Mortgage protection assurance | Contractual (lender condition) | The lender first, then family | Borrower | Before disbursement |
| Contents cover | Optional | Your belongings | Borrower | Optional |
| Title and legal cover | Contractual at purchase | The buyer | Borrower | At purchase |
How to verify which rule applies to you. Ask your lender for the specific clause in your offer letter or mortgage deed that requires insurance, and ask which insurer panel (if any) is approved. If the lender insists on a particular insurer, request the basis in writing. You can also confirm an insurer's licence and any consumer guidance through NAICOM.
Confirm early whether the lender requires a specific insurer or permits any licensed insurer.
For quick answers on how insurance and payment obligations work when buying with us, see our buyer FAQ.
National Insurance Commission regulatory framework
Mortgage Insurance Documents Required for Your Application
Mortgage insurance documents required for your application are the proof items your insurer and lender need to process cover. Prepare them together and the process moves fast.
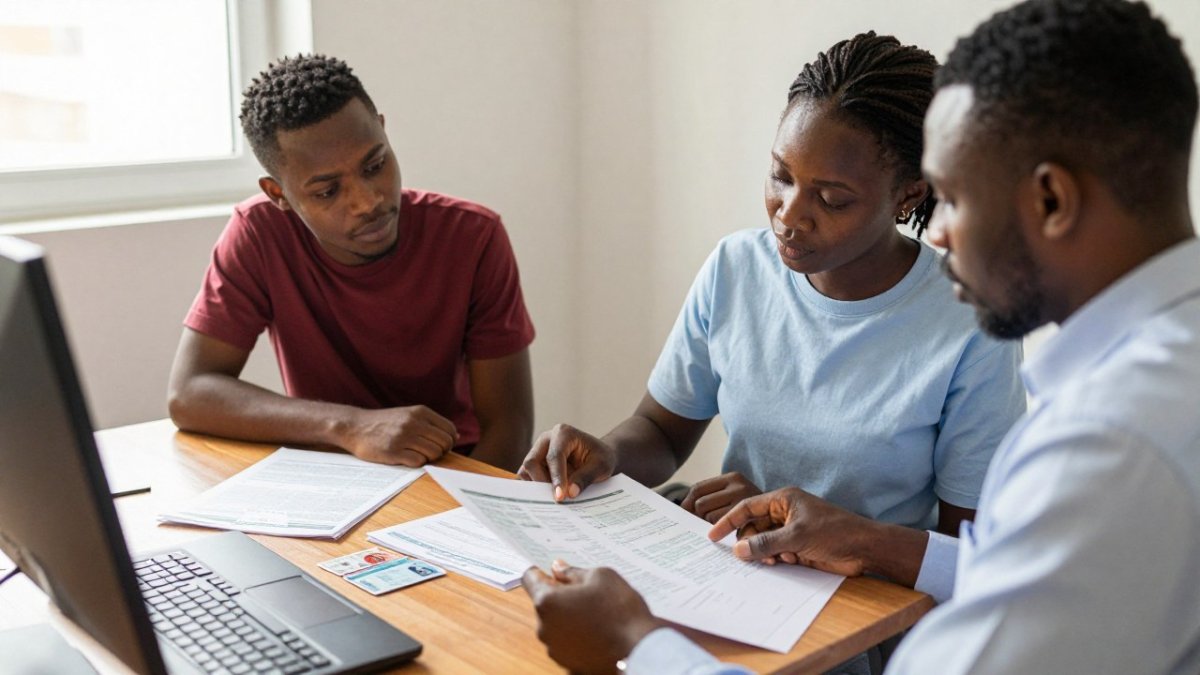
The checklist we walk buyers through:
- Valid identification (national ID, passport or driver's licence)
- Proof of residence (a recent utility bill)
- Bank statements for the last six months
- Employment or business income evidence
- Property valuation or purchase agreement
- Loan offer letter from the lender
- Completed proposal form
- Medical report, where the insurer asks
If you are still assembling your mortgage file, our step-by-step mortgage guide shows where insurance documents fit into the full application.
Mortgage Insurance Cost in Nigeria and How Premiums Are Set
Mortgage insurance cost in Nigeria is not a fixed statutory rate. It is quoted by insurers based on the risk they are taking, and the two covers are priced on completely different bases. Understanding the mechanism lets you sanity-check any quote you receive.
How fire and special perils premiums are built. The premium is a rate applied to the sum insured (normally the rebuild cost of the building, not the market price). The rate moves with:
- Construction type (concrete block versus timber or mixed materials)
- Occupancy (owner-occupied, rented, or vacant)
- Location and flood exposure
- Age and condition of the building
- Security measures (burglary cover, guards, alarms)
- Excess (the amount you agree to bear on each claim)
Because rates are commercially negotiated, quotes for the same building can differ between insurers.
How mortgage protection assurance is priced. This is life cover, so the premium depends on the borrower's age, health, smoking status and the sum assured, plus the policy term. Because the sum assured usually tracks the reducing loan balance, the premium is typically lower than a level-term policy of the same starting size. Insurers may require a medical report above a certain age or sum assured threshold.
What moves the number most.
- Sum assured: higher cover, higher premium, but underinsuring is worse, because it triggers average (reduced) settlement
- Age and health: older borrowers pay more for life cover
- Property location and construction: flood-prone or poorly built property costs more to insure
- Policy duration: longer terms mean more total premium
- Excess and exclusions: a higher excess lowers the premium but raises your out-of-pocket cost on a claim
How to compare quotes properly. Request written quotations from two or three NAICOM-licensed insurers and compare the exclusions, the excess, the sum assured basis (rebuild cost versus market value) and the claims settlement terms, not just the headline premium. The cheapest policy is worthless if it excludes the risk you actually face.
Watch out: a quote based on market value rather than rebuild cost can leave you underinsured after a total loss, because the insurer will apply average and pay only a proportion of the claim.
NAICOM insurance consumer guidance
Exclusions, Claims and Settlement: What Borrowers Should Check
Claims get paid or refused on the exclusions, so read them before you sign. Most disputes we hear about trace back to a clause the borrower never read.
Typical exclusions include:
- Wear and tear, plus poor maintenance
- War, riot and civil unrest, in many policies
- Unoccupied property beyond a set period
- Deliberate damage by the insured
- Undisclosed material facts at application
The claims process is straightforward if your documents are in order. Report the loss quickly, submit your evidence, and expect a loss adjuster to assess.
Settlement is usually paid to the lender up to the outstanding balance, with any remainder to you or your estate.
Watch out: underinsuring the building is the most common reason for a reduced payout. Insure for rebuild cost, not the price you paid.
Get a Mortgage Insurance Estimate Before You Commit
At Pennek, we help buyers see the full picture before they commit. Our mortgage package offers up to 70% financing on Pennek homes, with 30% equity and 10 to 12 year reducing balance repayment through partner mortgage banks. We also help you estimate repayments before you decide.
You do not have to guess your way through this. Reach out to our team for guidance on the process.
Insurance is the step most buyers leave to the last minute, and it is the one that can stop a completed purchase. Pennek builds communities across Lagos and Abuja with transparent processes, so you can see your mortgage and insurance costs before you commit. Our end-to-end support covers procurement, documentation and mortgage estimation, backed by over 15 years of creating residential communities. Get started with Pennek and secure your home with confidence.
Frequently Asked Questions
Is mortgage insurance compulsory for home loans in Nigeria?
There is no single law that makes mortgage insurance compulsory for every home loan. Lenders may make mortgage protection assurance and property insurance conditions of the offer letter before funds are released. Confirm with your lender and the applicable law which cover is legally required and which is a contractual condition. Read your offer letter carefully and ask which policies are conditions of the loan and which are optional.
What is the difference between mortgage protection insurance and home insurance?
Mortgage protection assurance pays off or reduces the outstanding loan balance if the borrower dies or, depending on the policy, becomes permanently disabled during the loan tenor. Home insurance in Nigeria covers the building and its contents against fire, special perils and other insured events. One protects the repayment plan, the other protects the physical property. Lenders commonly require both, and each has its own premium, sum assured and exclusions.
What documents are needed to apply for mortgage insurance?
Most insurers ask for a completed proposal form, valid identification such as a national ID, driver's licence or international passport, proof of residence through a recent utility bill, bank statements, the mortgage offer letter or loan agreement, and the property's title documents or valuation report. For credit-life cover, expect questions on age, date of birth and health. Requirements vary by insurance company, so confirm the exact list with your provider before submitting.
How much does mortgage insurance cost in Nigeria?
Mortgage insurance cost in Nigeria depends on the sum assured, the loan tenor, the age of the life assured, the property's risk profile and the insurer's assessment. Premiums are usually quoted as a percentage of the sum assured or loan balance. A younger borrower insuring a lower balance over a shorter tenor pays less than an older borrower with a larger loan. Ask each insurer for a written quote and compare the premium rate, coverage limits and exclusions, not just the headline figure.
